State site planning begins with the hazards at the address. Wildfire, flooding, drought, severe storms. Freeze events do not affect each State site in the same way. Construction, terrain, drainage, utilities, access, use, and local urgent states all shape the running plan.
The National Centers for Site Facts reports that 46 weather or climate disaster events with losses above $1 billion affected State from 1980 through 2024. NOAA's State series includes 19 wildfire, 14 drought, six flooding, four severe storm. Three freeze events. It reports no qualifying State event for 2024.
These are statewide, CPI-adjusted disaster statistics. They are not a forecast, a site-level loss estimate, or a count of each damaging event. Review the method in the archived NOAA State summary. NOAA retired updates after 2024, so these figures are a historical snapshot.
Translate broad risk into a property file
An owner cannot manage a statewide number. The useful unit is a site-clear risk register that identifies an observed state, in charge person, next action, due date. Finish proof. Build the register from current files and site states.
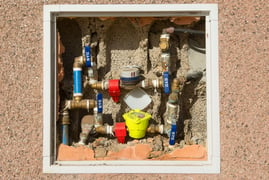
- Site facts: construction type, roof and major-system age, drainage, vegetation, slopes, access points, shutoffs. Known deferred upkeep.
- Local facts: local hazard maps, check rules, utility steps, and urgent contacts.
- Plan files: plan form, declarations, riders, deductibles, limits, exclusions, new term date, and carrier contact step.
- Running dependencies: vendors, keys, resident or tenant contacts, backup clear updates methods, and critical records.
Mark unknown facts as pending and assign someone to resolve them. A plan filled with guesses is difficult to use during an actual interruption.
Review the policy before the renewal deadline
State's plan market is changing. The State Team of Plan keeps a Sustainable Plan Plan and market snapshot that tracks admitted homeowners plans, distressed areas, FAIR Plan plan counts, premiums. Rate filings. The team describes the FAIR Plan as a last-resort plan pool for homeowners who cannot obtain limits through the traditional market.
That market context does not set what limits is available for a particular commercial, multifamily, or housing site. Ask a licensed plan skilled to explain the actual plan. Confirm which structures and work are covered, how deductibles apply, what exclusions or sublimits matter.
What records the carrier expects after a loss. Do not assume a physical upgrade will reduce a premium or secure new term. Carrier underwriting and plan terms control that result.
Prioritize maintenance with evidence
Risk work should be tied to observed states and vetted tips. A roof check may spot failed flashing. A drainage review may find blocked paths or ponding. A licensed vendor may record an power or building-system issue. Each finding should produce a scoped choice rather than a vague step to “prepare for weather.”
For each approved item, retain the check, bid, contract, permit facts. When local, finish photos, invoice, warranty. Final signoff. That record supports future upkeep choices and gives insurers, lenders, buyers, and teams a clearer past. It does not guarantee limits or prevent damage.
Plan for the first day of disruption
A practical response plan answers basic questions before the site team is under pressure:
- Who can authorize urgent stabilization within the care lease?
- How will residents, tenants, owners, and vendors receive checked updates?
- Where are shutoff steps, access facts, plans, and contact lists stored?
- Which vendors can respond, and what proof of license or plan is needed for the work?
- How will photos, expenses, temporary work, and carrier updates be logged?
Test the contact list and access step. Review the plan after a major building change, plan new term, vendor change, or incident. A stale plan can create false confidence.
Connect risk work to the capital plan
Some findings are upkeep items. Others belong in a multi-year cash plan. Split fast life-safety or active-damage work from near-term repairs and longer-term replacements. Record the basis for timing, the current estimate, and the choice owner. Revisit those guesses as bids, checks, and site states change.
Coastline explains its approach to upkeep and vendor control, multifamily care and planning, and an owner inquiry. Together, those areas help owners check whether risk observations are becoming logged running choices.
Use the data at the right scale
NOAA's series establishes that major weather and climate disasters have affected State across several hazard types. The Team of Plan files current statewide market states and legal plan. Site choices still need address-level facts, current plan language, skilled review. A record of completed work.
Ready to review the running controls around your site? Contact Coastline Equity to discuss the site and the records available.
Educational note: This article is main facts, not plan, legal, engineering, asset, or urgent-response advice. Consult licensed teams and public agencies for guidance clear to the site and current states.
Plain-Language Summary for Property Owners
Owners across Southern California need clear monthly cash flow. This applies to commercial sites. It also fits multifamily apartment buildings. Fast upkeep and clear notes keep good residents in place. Strong lease logs also help each commercial tenant pay on time.
Check vendor plan files before any crew steps on site. Compare written bids so repair costs stay fair and clear. Walk roofs, drains, and paths before heavy rain arrives. Keep clean cloud files for each lease and work order. Monthly budget checks help you spot high water bills early.
Quick Owner Action Steps
- Clear written rules stop costly legal mistakes in our state.
- Steady site walks catch small leaks before they grow big.
- Simple owner reports show your true net yield each month.
- Good planning cuts down on stress and surprise repair bills.
- Local market facts help you price each space right.
- An active team guards both your time and your equity.

 Explore Our Services
 Our Company
 About Our CEO
 Explore Our Blog