
About the Author: Anthony A. Luna
Anthony A. Luna is the Owner and CEO of Coastline Equity and author of Property Management Excellence. A licensed California real estate broker, he leads commercial and multifamily management operations across Southern California.
Services & Regional Coverage
Let's elevate the property management industry together. Share this blog with fellow investors.
More about Coastline Equity
-
Property Management Services
 Explore Our Services
Our team will handle all your property needs, offering specialized services such as in-depth inspections, liability management, staff recruitment and training, and round-the-clock maintenance—expert support tailored to the unique requirements of your real estate assets.
-
About Us
 Our Company
Our dedicated team transforms property management challenges into opportunities. From tenant management to streamlined rent collection and proactive maintenance.
-
Property Management Excellence
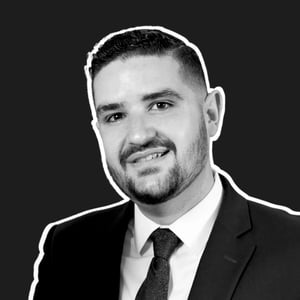 About Our CEO
Anthony A. Luna is CEO of Coastline Equity and author of Property Management Excellence. He writes about Southern California commercial and multifamily property management, owner decisions and the work required to follow repairs through completion.
-
Insights
 Explore Our Blog
Learn more about Coastline Equity's property management practices & processes and how we support our clients with education and a growth mindset. Coastline Equity Property Management is your partner as you continue to learn and grow.
News & Updates