Net operating income, or NOI, is the property's effective income minus its operating expenses for a stated period. It tells you what the building produced before debt payments and owner income taxes. The calculation is simple. The hard part is checking the rent, vacancy, and expense records behind it.
The NOI formula
NOI = effective gross income minus operating expenses. Fannie Mae defines effective gross income as net rental income plus commercial and other property income for the stated period. See the Fannie Mae Multifamily Guide. Keep the period consistent: a full year of income against a full year of expenses.
Start with scheduled rent. Subtract vacancy, concessions, and collection loss to estimate rent actually available. Add other property income, such as parking or laundry, when the records support it. That gives you effective income. Then subtract recurring expenses needed to operate the property, such as insurance, property taxes, owner-paid utilities, routine repairs, and management fees.
Mortgage principal and interest are not operating expenses in this calculation. NOI is therefore not the same as cash left after debt service. Keep planned capital projects and reserves visible as separate decisions, and state whether a lender or analyst adjusts them in a different underwriting measure.
A four-unit example
Suppose four apartments each have scheduled rent of $1,500 a month. This is a hypothetical example, not a market estimate.
- Scheduled rent: 4 x $1,500 x 12 = $72,000.
- Less vacancy and collection loss: $7,200.
- Plus other property income: $1,000.
- Effective income: $72,000 - $7,200 + $1,000 = $65,800.
- Less operating expenses: $30,000.
- NOI: $65,800 - $30,000 = $35,800.
A different vacancy or expense assumption changes the answer. Show the line items rather than presenting $35,800 as a property fact. A buyer should reconcile the rent roll to collections, confirm lease terms, and inspect invoices before relying on the seller's number.
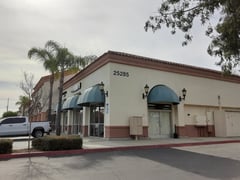
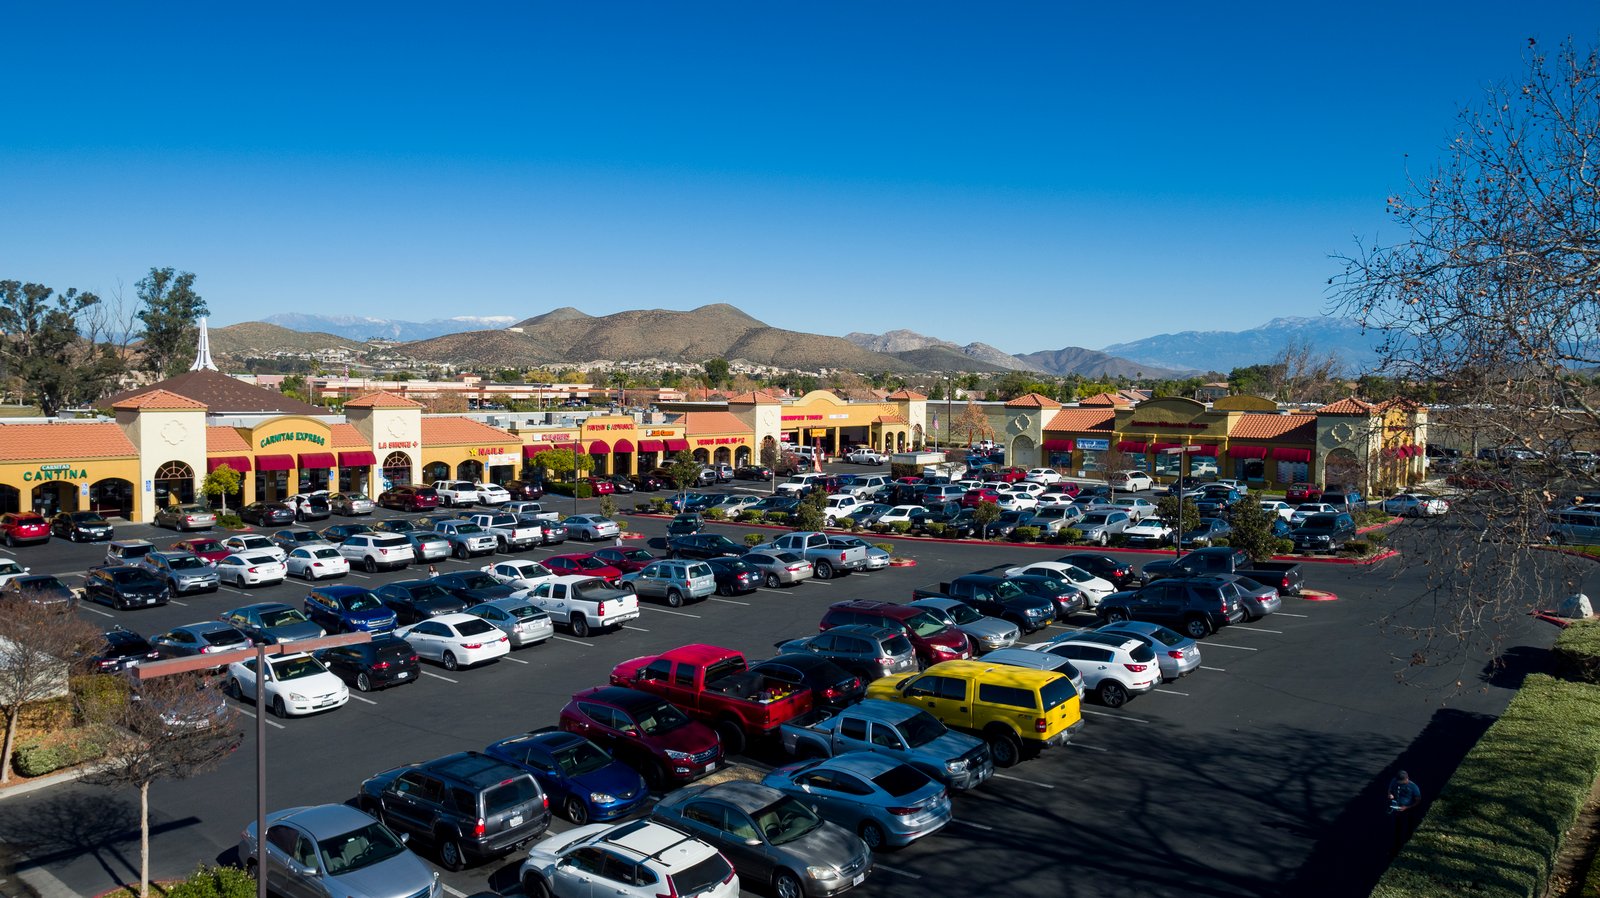
The same income-minus-operating-expense structure can be used for a leased shopping center, like the type of property shown in the photo above. Its income schedule may include base rent, commercial income, and lease-supported tenant reimbursements. Separate owner-paid costs from recoveries, then verify each line against the leases and operating records. The four-unit figures here do not estimate a shopping center's income.
What NOI leaves out
NOI does not tell you the purchase price, financing cost, capital work still required, or cash available to distribute. It also does not prove that every billed rent payment was collected. Read it next to the lease file, payment history, maintenance record, and a realistic first-year work plan. Our pre-purchase operating checklist explains how to test those records before closing.
NOI also enters an income-based value indication: for a stable expected income stream, an analyst may divide stabilized NOI by a supported capitalization rate. The OCC commercial real estate lending handbook describes that method. A changed NOI or cap rate changes the indication; it is not a guaranteed sale price or return. See our cap-rate sensitivity guide for the separate rate question.
Use it to manage the property
An owner can compare NOI across periods only after explaining what changed. Did collected rent improve? Did a repair move from routine expense to a capital project? Was a vacant unit counted as full rent in a forecast? Ask the manager to show the underlying activity and the decision needed, not just a higher or lower total.
If you already own a commercial or multifamily property in Southern California and your reports do not make those drivers clear, request a Property Management Performance Review. Coastline can discuss the building's management and reporting needs. The review is not an investment recommendation or a promise of returns.




 Explore Our Services
 Our Company
 About Our CEO
 Explore Our Blog